With interest rates on the way down, could house prices boom? Here’s what research suggests
- Written by The Conversation
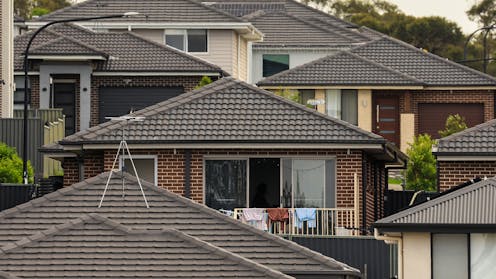
With the Reserve Bank of Australia easing monetary policy, interest rates are on the way down.
Already this year, mortgage pre-approvals had begun to rise, suggesting many aspiring home buyers are excited by the prospect of cheaper home loans.
With further cuts expected before the end of the year, some economists are predicting we could be on the cusp of another house price boom. Lower interest rates enable people to borrow more and potentially spend more on homes, bidding up prices.
So, how might the Reserve Bank’s actions affect home buying behaviour and the housing market more broadly? Research offers us some clues.
How rates affect prices
Research shows that when a central bank lowers its benchmark interest rate, mortgage interest rates usually follow suit.
We saw this following the Reserve Bank’s May decision to cut rates. Australia’s big four banks immediately announced similar reductions in rates for new and existing borrowers.
Lower rates reduce the cost of servicing a loan. This is a big deal for Australian home buyers, whose mortgages can be very large.
With the average house price in Australia now hitting about $1 million, an 80% loan saddles the typical home buyer with $800,000 in debt.
Back in March, the average interest rate on new mortgages was 6%. For the average million-dollar house, this implies a monthly repayment of around $4,796, using the standard formula for amortising loans.
After the Reserve Bank cut the cash rate by 0.25 percentage points, this implies a new monthly repayment of $4,669 – $127 less. That’s a small, but surely welcome, relief for mortgage holders.
Combined with the Reserve Bank’s prior rate cut in February, such borrowers are now saving more than $250 a month relative to the start of the year.

Everyone can borrow more
Lower rates can also improve the borrowing capacity of new home buyers.
Before a bank issues a new mortgage, it weighs the ability of a borrower to service the loan. It does this by considering the amount of income they’ll have left over after meeting typical expenses.
This is known as a borrower’s “net income surplus”, and the proportion of this that is used to service a loan is known as the “net surplus ratio”.
The maximum ratio is capped at 90%, but the typical mortgage is lent against a ratio of less than 70%.
If a household earns $100,000 per year and allocates 25% to expenses, it can afford $4,375 in monthly mortgage repayments at a 70% net surplus ratio.
Given the previous interest rate of 6%, this maximum monthly repayment implies the household can afford to borrow $680,000. But after a 0.25 percentage point rate cut, this household can now afford a $695,000 home loan.
And following the 0.50 percentage points of cuts we’ve seen since January, this household’s borrowing capacity is up by $30,000.
Pulling up the ladder
For an individual home buyer, this extra borrowing may be enough to secure that dream home. But the rate cut affects everyone at the same time, increasing the borrowing capacity of home buyers all over the country.
All of this extra mortgage credit feeds housing demand, which is likely to pour more fuel into an already overheated market.
Indeed, recent research indicates that a 0.25 percentage point cut in the cash rate will likely lead to a 1.5–2% increase in average house prices over the following one to two years.
That’s an extra $20,000 on the current $1 million average home value.
Research also suggests the impact of interest rates across local housing markets may be strongest where housing supply is tightest and houses are already more expensive.
Mortgages get bigger
While lower rates reduce the cost of a given mortgage, the average mortgage size needs to grow to keep up with higher prices.
Recall that the monthly payment associated with an 80% loan on a million-dollar home at 6% interest was $4,796. If the interest rate falls by 0.25 percentage points but house prices rise by 2%, the new monthly payment is little changed, at $4,762.
On top of this, the 20% down payment on that new home will now have increased – by $4,000.

Is there hope for first home buyers?
Despite the initial excitement of lower rates, aspiring home buyers may be disappointed to see the price of their dream home climb further out of reach. Some may end up no better off than they had been previously.
Others might try to snap up a home before lower rates are completely priced in – motivated by a fear-of-missing-out (FOMO). Research suggests it can take a year or more before house prices peak following a rate change.
And others still may decide to keep renting for the time being. Fortunately for them, recent research shows that changes in interest rates do not materially affect the rents that landlords charge their tenants.
Finally, one option is holding savings in the stock market while they wait, perhaps diversified via exchange-traded funds, as these assets usually rise in value following an interest rate cut.
It’s never a good idea to panic. It’s always important to think through your options before diving into the market. And remember, our discussion here is only for general information and is not intended to be financial advice. All investments carry risk.


