Owner beware: 4 reasons why selling part of Kiwibank could do more harm than good
- Written by The Conversation
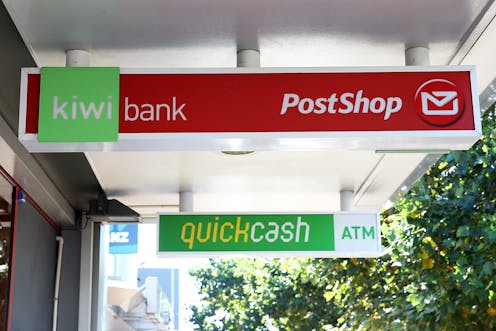
To sell, or not to sell – that is the question various governments have asked since Kiwibank was established in 2002. Now it’s the turn of the current National-led coalition to examine the bank’s state ownership.
Ministers have asked Kiwibank’s board to explore avenues for the bank’s expansion, potentially including private sector or Crown entity investment.
This comes just two years after the previous Labour government spent NZ$2.1 billion to secure complete ownership of Kiwibank, and is part of the coalition’s drive for productivity, growth and public sector efficiency.
The latest attempt to help the bank prosper while staying fully New Zealand-owned should also be seen in the context of the recent Commerce Commission draft report on banking services, which identifies Kiwibank as a market disruptor.
If properly capitalised, the report says, Kiwibank should make New Zealand banking more competitive. Supporters of partial privatisation or publicly listing a proportion of Kiwibank shares agree. They also argue it would boost the stock market and funnel profits back to New Zealanders.
The government has not proposed anything specific yet. But any plans to part-privatise Kiwibank so soon after the state effectively bailed it out deserve close scrutiny. Such a move could well do more harm than good, for four main reasons.
1. Banking concentration is normal
New Zealand’s historical banking concentration and the market domination of four large Australian-owned banks is not going to change any time soon.
But a concentrated banking sector is not at all bad, or even abnormal, and occurs in many countries. Three banks in the Netherlands, for example, currently own 84% of total banking assets. The smallest, ABN AMRO, is larger than all of New Zealand’s banks combined.
Despite this, the Dutch are less vocal about lack of competition and associated high profit margins. There is an acceptance, especially among European Union bank regulators, that the alternative of more small banks is not a panacea.
Small banks in EU countries such as Spain and the Netherlands have failed more often than large ones. Moreover, innovation in banking and finance comes mainly from large banks.
2. Capital investment and growth
The notion that more capital will foster growth puts the cart before the horse. As fans of TV investment shows Shark Tank or Dragons’ Den will know, only firms with a compelling value proposition attract funding.
Kiwibank’s track record leaves something to be desired. For example, the press release accompanying its 2023 results listed the introduction of Apple Pay as an important highlight. Other banks began offering this service in 2016.
Furthermore, at 7.5%, the bank’s return on equity is the lowest of the largest six banks. And its core capital ratio has not increased since 2018, making it harder to meet increasing Reserve Bank capital requirements.
After a minor capital injection of $225 million last year, Kiwibank chief executive Steve Jurkovich said the bank’s loan book could significantly increase. According to the Reserve Bank’s financial strength dashboard, however, the value of Kiwibank’s net loans and advances grew by 2.7% and 1.8% respectively in the quarters ending December 2023 and March 2024.
That was not significantly different from growth in previous quarters going back to 2018, which averaged 2.3%. In other words, Kiwibank’s own experience shows flaws in the capital-before-growth narrative.
3. Foreign ownership by stealth
In an ideal world – with deep and liquid capital markets, and a large, growing and productive economy – having a 100% Kiwi-owned contender bank would work.
In reality, New Zealand lacks these features. In fact, Kiwibank’s ownership restrictions – which preclude floating or selling shares directly – have seen previous owners surrender their holdings to the government.
Part-privatisation would therefore require shares to be sold at a deep discount. And, as the sale of Kiwi Wealth to Fisher Funds in 2022 suggests, this may ultimately be financed by foreign private equity.
This could be achieved by way of a leveraged buyout, where a foreign private equity firm lends large sums of money to, say, a KiwiSaver fund to buy shares. Technically, the KiwiSaver fund would be the 100% New Zealand-owned firm holding the Kiwibank shares. But that ownership would be largely in name only.
The New Zealand owner would pay hefty interest expenses to the private equity firm. And it’s likely the private equity firm would want to tear Kiwibank apart to cut costs and improve efficiency.
By comparison, perhaps the current arrangement – four dominant banks owned by parent banks in a geographically and culturally close country – is not that bad.
4. Unintended consequences
Finally, there is the problem of reputation and moral hazard. Investors would be sceptical if Kiwibank were to be partly privatised, as history shows its ownership seems to depend on the government of the day.
Given that uncertainty, investors might only buy shares sold at a deep discount, or if the shares offered a high return – the kind private equity firms require.
In turn, this could prompt the bank to engage in excessive risk taking, which creates the kind of disruption no one wants. Buyers may also want a guarantee they can put the shares back to the government if the bank fails to perform well.
Rather than rush to part-privatise, Kiwibank should focus on strengthening its capital base, improving performance, and establishing a clear track record of growth and innovation.
Only then should any change in ownership be considered. The path to a more competitive banking sector in New Zealand requires patience, strategic planning and a realistic assessment of market conditions, not hasty structural changes.


